Comparing on the same basis
Short lets and longer tenancies produce income differently. Compare the same property over the same period, then deduct the relevant operating costs from each option. A headline nightly rate and a monthly rent are not directly comparable.
What actually differs
Structural differences between the two arrangements, before any figures are applied.
- Income pattern
Short let: Varies by night, season and demand. Some weeks empty.
Long-term tenancy: Fixed monthly rent while tenanted.
- Utilities and broadband
Short let: Normally paid by the owner.
Long-term tenancy: Normally paid by the tenant.
- Turnover costs
Short let: Cleaning, linen and consumables for every stay.
Long-term tenancy: Typically only between tenancies.
- Furnishing
Short let: Furnished and equipped to a guest standard. Furnishing and replacement budgets need to reflect guest use.
Long-term tenancy: Often let unfurnished or part-furnished.
- Access to the property
Short let: Owner can block dates and use the property.
Long-term tenancy: Tenant has exclusive possession for the term.
- Management
Short let: Active operation: pricing, guests, turnovers, maintenance.
Long-term tenancy: Periodic: rent collection, inspections, repairs.
- Rules to check
Short let: Lease, planning position, insurance, mortgage, and local limits where they apply.
Long-term tenancy: Standard letting obligations for the tenure.
| Consideration | Short let | Long-term tenancy |
|---|---|---|
| Income pattern | Varies by night, season and demand. Some weeks empty. | Fixed monthly rent while tenanted. |
| Utilities and broadband | Normally paid by the owner. | Normally paid by the tenant. |
| Turnover costs | Cleaning, linen and consumables for every stay. | Typically only between tenancies. |
| Furnishing | Furnished and equipped to a guest standard. Furnishing and replacement budgets need to reflect guest use. | Often let unfurnished or part-furnished. |
| Access to the property | Owner can block dates and use the property. | Tenant has exclusive possession for the term. |
| Management | Active operation: pricing, guests, turnovers, maintenance. | Periodic: rent collection, inspections, repairs. |
| Rules to check | Lease, planning position, insurance, mortgage, and local limits where they apply. | Standard letting obligations for the tenure. |
Build your twelve-month comparison
Use your property's figures in both columns. Net operating income for each option is gross receipts less the operating costs that option carries. Keep finance costs and personal tax out of that line and consider them separately, as cash flow. This is a planning worksheet, not accounting or tax advice.
Twelve-month comparison
- Column A: expected annual rent under a tenancyUse a realistic local figure for the same property over the same twelve months.
- Column B: expected annual booking revenueNightly rate multiplied by the nights you genuinely expect to sell, not the nights in the year.
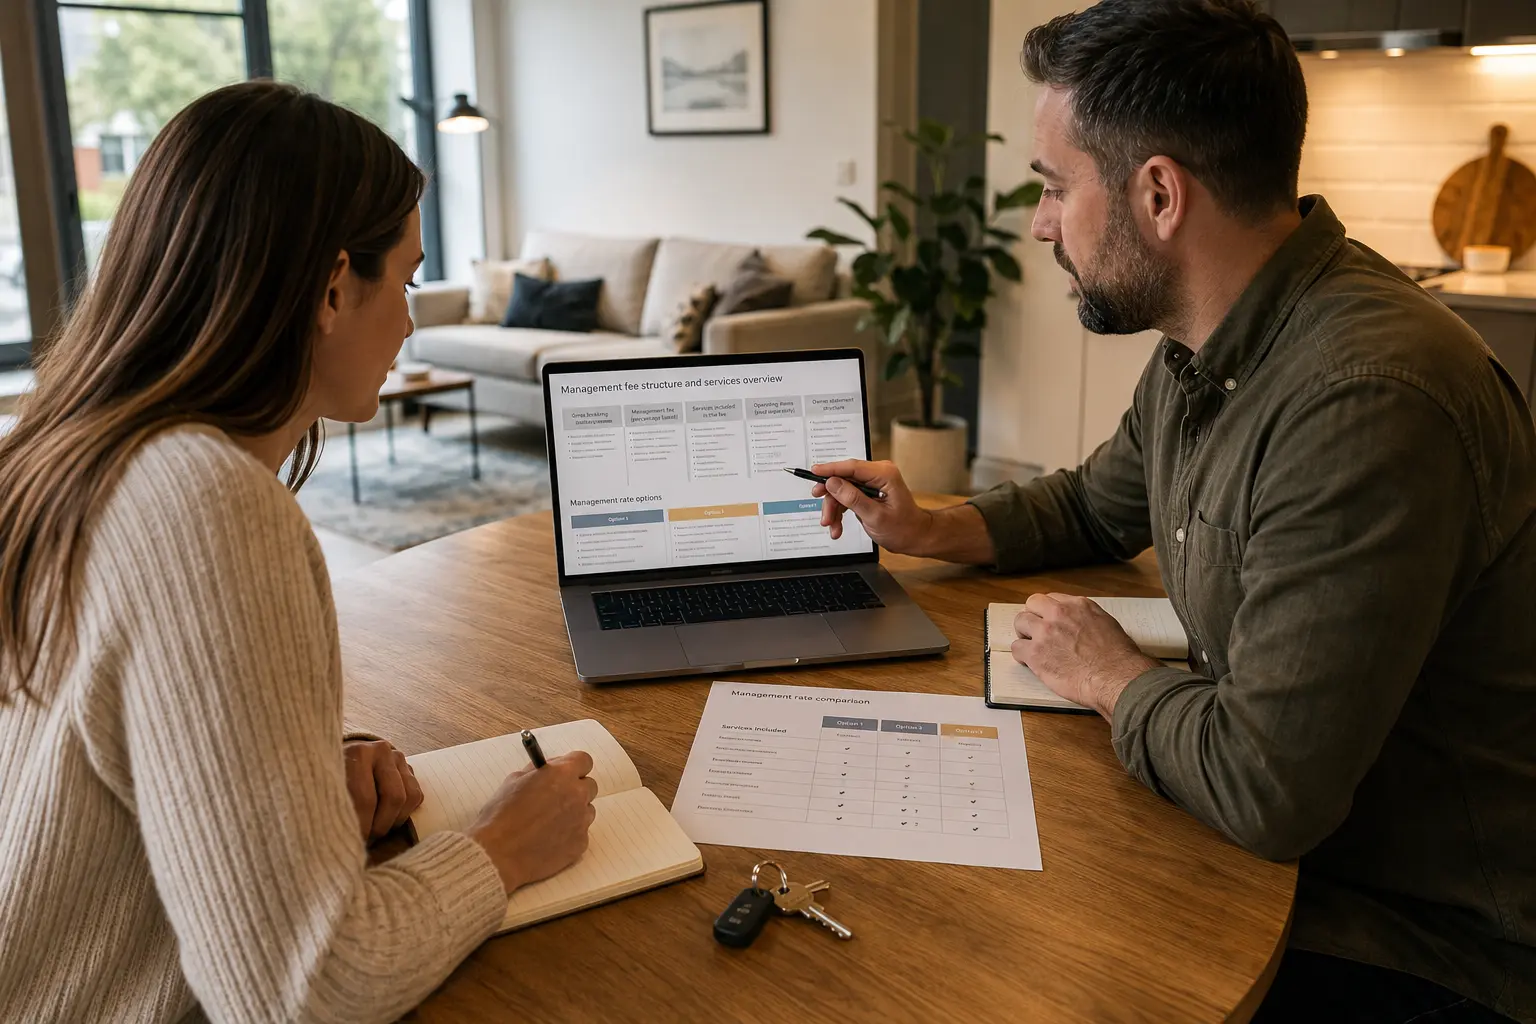
- Deduct each option's letting costsColumn A: letting or management fees and a void allowance. Column B: platform fees and management — with Hostahome 20%, 18% or 15% of booking revenue depending on the term.
- Deduct turnover costs from column BCleaning and linen per stay, multiplied by the number of stays — not the number of nights.
- Deduct running costs from each column as they applyUtilities, broadband, consumables, replacements and service charges often sit with the owner in column B and with the tenant in column A. Council tax or business rates depend on the arrangement, so put each cost in the column that actually bears it and avoid counting it twice.
- Deduct repairs and maintenance from both columnsBoth options carry repairs. Estimate each on its own basis rather than applying one figure to both.
- Read the two net operating income linesGross receipts less operating costs, for each column.
- Consider finance and tax separatelyMortgage interest and other finance costs, and your personal tax position, affect cash flow but sit outside net operating income. Treat them as a separate line and take professional advice on tax treatment.
- Compare the two bottom linesThen ask how much the difference is worth to you against the difference in flexibility and effort.
Usable nights, not just rate
Owners tend to anchor on the nightly rate because it is the number they can see on a listing. The figure that decides the year is how many nights the property can actually be let: nights lost to the gap between stays, nights you keep for your own use, minimum-stay rules, seasonal demand, and any limit that applies where the property is. In Greater London that last point can be a hard number. The worksheet can cover any consistent twelve-month comparison period, but London's statutory limit is counted by calendar year. Read howthe 90-night rule and what it covers before completing the comparison.
Area-level occupancy or income figures do not settle the answer for one property. A property review instead considers how that specific home could be operated and which assumptions need testing.
The non-financial side
Flexibility is the usual reason owners choose short-letting even when the net difference is modest: the property can remain available to you, and bringing it back into your own use or selling it is generally more flexible than under a tenancy — subject to existing bookings, your agreements and the rights that apply. Against that, a short let is an operating business rather than a passive holding, which is why most owners either commit real time to it or hand it to a manager. A tenancy is quieter and more predictable, and for some properties that is simply the better answer.
Which suits which owner
Short-letting tends to suit a well-located, well-presented property that the owner may want access to, where the lease and local rules allow it, and where the owner is comfortable with income that varies. A tenancy tends to suit an owner who wants predictability, who does not need access, or whose property, honestly assessed, would not stand out to guests.
If you would like that assessment for a specific property — including the possibility that we recommend a tenancy — that is what the property review is for.